• Log InLog In
  • Register
Liquid`
Team Liquid Liquipedia
EDT 15:03
CEST 21:03
KST 04:03
  • Home
  • Forum
  • Calendar
  • Streams
  • Liquipedia
  • Features
  • Store
  • EPT
  • TL+
  • StarCraft 2
  • Brood War
  • Smash
  • Heroes
  • Counter-Strike
  • Overwatch
  • Liquibet
  • Fantasy StarCraft
  • TLPD
  • StarCraft 2
  • Brood War
  • Blogs
Forum Sidebar
Events/Features
News
Featured News
[ASL22] Ro8 Preview: In A Tizzy6[ASL22] Ro16 Preview: Holy Diver5[ASL22] Ro16 Preview: Rough Waters10[ASL22] Ro24 Preview: Siren's Call8[ASL22] Ro24 Preview: Summer's End9
Community News
Weekly Cups (Sep 13-20): herO scores triple1BSL Season 235Weekly Cups (Sep 7-12): SHIN, ByuN, MaxPax double down1StarCraft open world shooter announced at BlizzCon101Weekly Cups (Aug 30-Sep 7): herO thrives amid growing schism10
StarCraft 2
General
Blizzard Classic Cup @ BlizzCon 2026 - $100k prize pool The Death of Cheese: From a Professional Cheeser Weekly Cups (Sep 13-20): herO scores triple Balance hotfix patch 5.0.16b (July 16) StarCraft open world shooter announced at BlizzCon
Tourneys
2026 GSTL Announcement Sparkling Tuna Cup - Weekly Open Tournament RSL Revival: Season 6 - Qualifiers and Main Event RSL goes to London! 2026 Offline Finals Nov 21-22 SC2 AI Tournament 2026 Fall
Strategy
[H] ZvP Mid-Late Game: Stalkers Collossi HT
Custom Maps
Nexus Wars 2021 GUIDE [M] (2) Industrial Park
External Content
Mutation # 544 Double Trouble The PondCast: SC2 News & Results Mutation # 543 Enhanced Defenses Mutation # 542 The Ascended
Brood War
General
Bot on ladder an AI researcher's take on the ladder bot New 3v3 BGH Ladder (and more) on ShieldBattery! Recent recommended BW games BSL Season 23
Tourneys
[IPSL] IPSL is Back With Winter 26-27! [ASL22] Ro8 Day 1 [BSL23] SM: Ret vs TerrOr -> DragOn vs StRyKeR [Megathread] Daily Proleagues
Strategy
Cliff Jump Revisited (1 in a 1000 strategy) Replay Review Process - What do you do? Simple Questions, Simple Answers Odyssey Mineral Stack Saturation
Other Games
General Games
Warcraft III: The Frozen Throne Nintendo Switch Thread Stormgate/Frost Giant Megathread EVE Corporation Diablo IV
Dota 2
Dota 2 Champions League Season 3 Begins April 25! Official 'what is Dota anymore' discussion
League of Legends
[TL LoL EUW IHs] Teemo shall perish
Heroes of the Storm
Heroes of the Storm 2.0
Hearthstone
Deck construction bug
TL Mafia
TL Mafia Community Thread
Community
General
US Politics Mega-thread Artificial Intelligence Thread Things Aren’t Peaceful in Palestine All you football fans (soccer)! Russo-Ukrainian War Thread
Fan Clubs
MarineLorD Fan Club The Creator Fan Club The ShoWTimE Fan Club
Media & Entertainment
Movie Discussion! [Manga] One Piece Diablo Animated Series on Netflix
Sports
Football (Soccer) Thread TeamLiquid Health and Fitness Initiative For 2023 MLB/Baseball 2023
World Cup 2022
Tech Support
Computer Build, Upgrade & Buying Resource Thread
TL Community
Recent Gifted Posts
Blogs
Gaming Intensity, Problemati…
TrAiDoS
38 yo Retired SWE loo…
PurE)Rabbit-SF
Can Bots Beat Pros?? Starcr…
namkraft
[meme] I finally understa…
LUCKY_NOOB
Regacy Esports:Our Goa…
regacyesports
Dreaming of BW patches (mod…
c3rberUs
Customize Sidebar...

Website Feedback

Closed Threads


Active: 7048 users

My Car Loan

Blogs > micronesia
Post a Reply
Normal
micronesia
Profile Blog Joined July 2006
United States24799 Posts
Last Edited: 2011-04-21 22:52:12
April 21 2011 22:49 GMT
#1
[image loading]


+ Show Spoiler [Data] +

Here is the code for the "New Balance" cells: =D2*(1+$H$1/12)

As I dragged the code down to each additional cell the D2 stepped to D3, D4, etc. H1 is the cell which has the interest rate of 0.0499.

[image loading]


*****
ModeratorThere are animal crackers for people and there are people crackers for animals.
Cauld
Profile Joined February 2010
United States350 Posts
Last Edited: 2011-04-21 23:01:33
April 21 2011 23:00 GMT
#2
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.
micronesia
Profile Blog Joined July 2006
United States24799 Posts
Last Edited: 2011-04-21 23:03:36
April 21 2011 23:02 GMT
#3
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.
ModeratorThere are animal crackers for people and there are people crackers for animals.
eNtitY~
Profile Joined January 2007
United States1293 Posts
April 21 2011 23:05 GMT
#4
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/
http://www.starcraftdream.com
micronesia
Profile Blog Joined July 2006
United States24799 Posts
April 21 2011 23:08 GMT
#5
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).
ModeratorThere are animal crackers for people and there are people crackers for animals.
Cauld
Profile Joined February 2010
United States350 Posts
Last Edited: 2011-04-21 23:15:12
April 21 2011 23:11 GMT
#6
On April 22 2011 08:02 micronesia wrote:
Show nested quote +
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.
eNtitY~
Profile Joined January 2007
United States1293 Posts
Last Edited: 2011-04-21 23:15:30
April 21 2011 23:14 GMT
#7
On April 22 2011 08:08 micronesia wrote:
Show nested quote +
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).


Yeah just checked, it's 9.4 and I've already paid $4000 in interest .

I'll end up paying ~$10k in interest before it's done. I also co-signed with my dad (Very high 700s CS) but didn't do automatic payments and also had a 72 month contract.
http://www.starcraftdream.com
Ryps
Profile Blog Joined May 2010
Romania2740 Posts
Last Edited: 2011-04-21 23:16:47
April 21 2011 23:14 GMT
#8
So... what car did you get ? and whos pic is at the bottom
Looks like its a mazda hatchback ?
Myles
Profile Blog Joined March 2010
United States5162 Posts
April 21 2011 23:18 GMT
#9
On April 22 2011 08:08 micronesia wrote:
Show nested quote +
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).


Yea, you got 3.3% lower rate than I did when I co-signed with my dad for a 17k loan in '07. Of course, now that I'm older/wiser I feel I could have got a better deal, but that's life.
Moderator
eNtitY~
Profile Joined January 2007
United States1293 Posts
April 21 2011 23:23 GMT
#10
Fuck you both.
http://www.starcraftdream.com
tofucake
Profile Blog Joined October 2009
Hyrule19257 Posts
April 21 2011 23:24 GMT
#11
Your last payment is off because that's how it works out. Your last payment due will only be for the remaining principal, as you'll have paid off the interest on the 59th payment.

As for the payment, you're close. It's actually
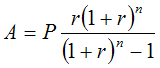
[image loading]
Where r is the periodic interest rate. For calculating payments, it'll be daily. The reason your interest decreases over time is because at the start of the loan, you have a higher principal balance (P above).

The actual payment (assuming Simple Interest here) is:
Fees = Total amount paid minus any fee balance (late fees, typically)
Interest = Current principal balance times the periodic interest rate (APR / 365) times the number of days since last payment plus any outstanding interest due
Principal is the rest

On an Actuarial loan, that 365 could be 360, 363, or 365.
On a Rule of 78s loan you're getting totally shafted in every way possible (Ro78s is illegal in 17 states because of it's terribadness)

What this means is that, as long as you don't have a Rule of 78s loan, paying early and overpaying will reduce overall how much you pay. This may seem counter intuitive (wtf pay more = pay less?) but the financing company (or bank) gets all of its profit off of the interest. By overpaying you prematurely reduce the principal balance, so if you paid $400 every month instead of $377.56 you'd end up paying off the loan a couple months early, which reduces the number of days calculated for how much interest is due (so you don't pay that interest at all).

By paying early, you're cutting short the number of days interest is calculated on as well. For example, if you payed May 1st, you'd put $40.84, but if you pay a day earlier $39.48. So that's another $1.36 that goes directly to principal, which will reduce how much you pay next month.
Liquipediaasante sana squash banana
tofucake
Profile Blog Joined October 2009
Hyrule19257 Posts
April 21 2011 23:25 GMT
#12
On April 22 2011 08:11 Cauld wrote:
Show nested quote +
On April 22 2011 08:02 micronesia wrote:
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.
Principal never ever ever increases by anything other than a bounced check. EVER
Liquipediaasante sana squash banana
Michaelj
Profile Joined February 2008
United States186 Posts
April 21 2011 23:26 GMT
#13
They're not "front-loading" the interest. They do calculate your payments such that you can 60 equal payments. But if your loan agreement allows you to prepay your loan, you would find that you could just pay for the remaining principal, and not pay any of the extra interest.

Example:

$20,000 loan
1% interest
$300 monthly payment

Period 1: $20,000 remaining principal, $200 interest payment, $100 principal payment
Period 2: $19,900 remaining principal, $199 interest payment, $101 principal payment
Period 3: $19,799 remaining principal, $198 interest payment, $102 principal payment

So you see it's pretty clear that you are just paying the interest on the principal that you currently have outstanding. The car companies have just adjusted your monthly payment amount such that you pay an even amount every month, and everything takes care of itself neatly by the time you 5 years are up.

TLDR: The suggested payment amount presumes you take the full 5 years to pay. If you have $15k in principal left, and want to pay if off in full today, you can and not pay a dime of extra interest
---
Michaelj
Profile Joined February 2008
United States186 Posts
April 21 2011 23:28 GMT
#14
On April 22 2011 08:25 tofucake wrote:
Show nested quote +
On April 22 2011 08:11 Cauld wrote:
On April 22 2011 08:02 micronesia wrote:
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.
Principal never ever ever increases by anything other than a bounced check. EVER


You'd be surprised... in the housing boom people would get negative amortization loans that meant they would pay LESS than interest. They'd try to flip the house as soon as they could.

http://en.wikipedia.org/wiki/Negative_amortization
---
micronesia
Profile Blog Joined July 2006
United States24799 Posts
April 21 2011 23:30 GMT
#15
On April 22 2011 08:11 Cauld wrote:
Show nested quote +
On April 22 2011 08:02 micronesia wrote:
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.

If you are right (and what you said makes sense) then my payoff amount at the end of the first month would have just been the 20,083 dollars... I might be remembering incorrectly but I am pretty sure that's not what it was. If it WAS then it works exactly how my 'high school math class' explained and is consistent with your explanation.

Do you know why they inform me in my loan information how much of my payment went to interest and how much went to principal? Was it just to show how much interest I accrued that prior month? And I guess also to show how much I knocked down the principal that month?
ModeratorThere are animal crackers for people and there are people crackers for animals.
micronesia
Profile Blog Joined July 2006
United States24799 Posts
Last Edited: 2011-04-21 23:35:29
April 21 2011 23:34 GMT
#16
On April 22 2011 08:24 tofucake wrote:
Your last payment is off because that's how it works out. Your last payment due will only be for the remaining principal, as you'll have paid off the interest on the 59th payment.

As for the payment, you're close. It's actually
[image loading]
Where r is the periodic interest rate. For calculating payments, it'll be daily. The reason your interest decreases over time is because at the start of the loan, you have a higher principal balance (P above).

The actual payment (assuming Simple Interest here) is:
Fees = Total amount paid minus any fee balance (late fees, typically)
Interest = Current principal balance times the periodic interest rate (APR / 365) times the number of days since last payment plus any outstanding interest due
Principal is the rest

On an Actuarial loan, that 365 could be 360, 363, or 365.
On a Rule of 78s loan you're getting totally shafted in every way possible (Ro78s is illegal in 17 states because of it's terribadness)

What this means is that, as long as you don't have a Rule of 78s loan, paying early and overpaying will reduce overall how much you pay. This may seem counter intuitive (wtf pay more = pay less?) but the financing company (or bank) gets all of its profit off of the interest. By overpaying you prematurely reduce the principal balance, so if you paid $400 every month instead of $377.56 you'd end up paying off the loan a couple months early, which reduces the number of days calculated for how much interest is due (so you don't pay that interest at all).

By paying early, you're cutting short the number of days interest is calculated on as well. For example, if you payed May 1st, you'd put $40.84, but if you pay a day earlier $39.48. So that's another $1.36 that goes directly to principal, which will reduce how much you pay next month.

Oh okay I should have realized that it compounds daily instead of monthly... well I guess that information wasn't given to me directly so I can't blame myself for not knowing :p

And I guess from what I'm reading the type of 'front loading' I am thinking of would only happen with special conditions in the agreement.

On April 22 2011 08:26 Michaelj wrote:
They're not "front-loading" the interest. They do calculate your payments such that you can 60 equal payments. But if your loan agreement allows you to prepay your loan, you would find that you could just pay for the remaining principal, and not pay any of the extra interest.

Example:

$20,000 loan
1% interest
$300 monthly payment

Period 1: $20,000 remaining principal, $200 interest payment, $100 principal payment
Period 2: $19,900 remaining principal, $199 interest payment, $101 principal payment
Period 3: $19,799 remaining principal, $198 interest payment, $102 principal payment

So you see it's pretty clear that you are just paying the interest on the principal that you currently have outstanding. The car companies have just adjusted your monthly payment amount such that you pay an even amount every month, and everything takes care of itself neatly by the time you 5 years are up.

TLDR: The suggested payment amount presumes you take the full 5 years to pay. If you have $15k in principal left, and want to pay if off in full today, you can and not pay a dime of extra interest

I hope you are right and that's how my loan is working because that's better for us!
ModeratorThere are animal crackers for people and there are people crackers for animals.
tofucake
Profile Blog Joined October 2009
Hyrule19257 Posts
April 21 2011 23:40 GMT
#17
On April 22 2011 08:28 Michaelj wrote:
Show nested quote +
On April 22 2011 08:25 tofucake wrote:
On April 22 2011 08:11 Cauld wrote:
On April 22 2011 08:02 micronesia wrote:
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.
Principal never ever ever increases by anything other than a bounced check. EVER


You'd be surprised... in the housing boom people would get negative amortization loans that meant they would pay LESS than interest. They'd try to flip the house as soon as they could.

http://en.wikipedia.org/wiki/Negative_amortization

Yes but those were sub-prime house loans, not car loans. Please trust me. This is literally what I do for a living.
Liquipediaasante sana squash banana
Cauld
Profile Joined February 2010
United States350 Posts
April 21 2011 23:53 GMT
#18
I was speaking in the general sense about loans, I wouldn't ever expect a car loan to allow a payment less than the interest amount, since the underlying asset is generally decreasing in value over time.
a176
Profile Blog Joined August 2009
Canada6688 Posts
April 22 2011 00:01 GMT
#19
On April 22 2011 08:14 eNtitY~ wrote:
Show nested quote +
On April 22 2011 08:08 micronesia wrote:
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).


Yeah just checked, it's 9.4 and I've already paid $4000 in interest .

I'll end up paying ~$10k in interest before it's done. I also co-signed with my dad (Very high 700s CS) but didn't do automatic payments and also had a 72 month contract.


why in the world would you agree to an-almost 10% interest rate, completely ridiculous
starleague forever
eNtitY~
Profile Joined January 2007
United States1293 Posts
Last Edited: 2011-04-22 00:12:11
April 22 2011 00:10 GMT
#20
On April 22 2011 09:01 a176 wrote:
Show nested quote +
On April 22 2011 08:14 eNtitY~ wrote:
On April 22 2011 08:08 micronesia wrote:
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).


Yeah just checked, it's 9.4 and I've already paid $4000 in interest .

I'll end up paying ~$10k in interest before it's done. I also co-signed with my dad (Very high 700s CS) but didn't do automatic payments and also had a 72 month contract.


why in the world would you agree to an-almost 10% interest rate, completely ridiculous


Well....

[image loading]

And being 20.


Man that was retarded. Can you refinance auto loans if your car is worth more than the balance?
http://www.starcraftdream.com
a176
Profile Blog Joined August 2009
Canada6688 Posts
April 22 2011 00:30 GMT
#21
do lenders want to lose money? lol
starleague forever
micronesia
Profile Blog Joined July 2006
United States24799 Posts
Last Edited: 2011-04-22 03:49:04
April 22 2011 01:11 GMT
#22
I think you can. I researched refinancing my car loan last summer and I was able to do it... the interest rate I could get wasn't much better than my current one so the refinancing fee would make me just about break even... but it was available.
ModeratorThere are animal crackers for people and there are people crackers for animals.
micronesia
Profile Blog Joined July 2006
United States24799 Posts
April 22 2011 01:59 GMT
#23
On April 22 2011 08:14 Drey wrote:
So... what car did you get ? and whos pic is at the bottom
Looks like its a mazda hatchback ?

Wow sorry I completely forgot to respond to your post... if you searched for the thread you'd see it is a.... 2008 Mazdaspeed 3.
ModeratorThere are animal crackers for people and there are people crackers for animals.
tofucake
Profile Blog Joined October 2009
Hyrule19257 Posts
April 22 2011 03:48 GMT
#24
9.4 is actually a very good interest rate. If you have bad credit it can be 30%. And no. If you fail to pay, the lendor repossesses the car and holds it for some period of time. During this time you can redeem it by paying the repo fees and some penalties. After this time the lendor reports you as having defaulted and can resell/relend the car.

As for refinancing, none of the contracts my company has allows it, so I don't know.
Liquipediaasante sana squash banana
eNtitY~
Profile Joined January 2007
United States1293 Posts
April 22 2011 19:22 GMT
#25
Well that make's me feel a bit better I guess.
http://www.starcraftdream.com
Normal
Please log in or register to reply.
Live Events Refresh
Monday Night Weeklies
16:00
#64
RotterdaM896
TKL 396
TaKeTV 348
IndyStarCraft 271
SteadfastSC163
ZombieGrub114
BRAT_OK 90
LiquipediaDiscussion
[ Submit Event ]
Live Streams
Refresh
StarCraft 2
RotterdaM 896
TKL 396
ByuN 387
IndyStarCraft 271
SteadfastSC 163
ProTech122
ZombieGrub114
BRAT_OK 90
MindelVK 14
EnDerr 1
StarCraft: Brood War
Shuttle 805
Britney 319
BeSt 124
firebathero 90
Trap 38
910 31
scan(afreeca) 20
yabsab 7
Counter-Strike
fl0m1157
pashabiceps988
Heroes of the Storm
Grubby3192
Liquid`Hasu439
Other Games
Liquid`RaSZi3357
FrodaN1129
Beastyqt787
B2W.Neo688
ceh9538
mouzStarbuck270
ArmadaUGS138
QueenE117
C9.Mang0103
KnowMe102
Dewaltoss86
Trikslyr64
UpATreeSC60
Mew2King50
Chillindude21
Organizations
Other Games
BasetradeTV44
[ Show 22 non-featured ]
StarCraft 2
• kabyraGe 149
• mYiSmile125
• StrangeGG 7
• intothetv
• IndyKCrew
• AfreecaTV YouTube
• Migwel
• Kozan
StarCraft: Brood War
• blackmanpl 33
• 80smullet 20
• Azhi_Dahaki11
• Michael_bg 11
• STPLYoutube
• ZZZeroYoutube
• BSLYoutube
Dota 2
• C_a_k_e 5327
• masondota21576
League of Legends
• Nemesis2361
• TFBlade1147
• Noizen103
Other Games
• imaqtpie960
• Shiphtur270
Upcoming Events
Sparkling Tuna Cup
14h 57m
Afreeca Starleague
14h 57m
Light vs EffOrt
OSC
16h 57m
PiGosaur Cup
1d 4h
Kung Fu Cup
1d 15h
The PondCast
2 days
Replay Cast
3 days
Korean StarCraft League
4 days
CranKy Ducklings
4 days
GSL
5 days
[ Show More ]
Yamato Cup
5 days
Replay Cast
6 days
Afreeca Starleague
6 days
WardiTV Weekly
6 days
Liquipedia Results

Completed

Super Anchor Qualifying S3
Blizzard Classic Cup 2026
Big Dog Cup 2026 Div 1

Ongoing

ASL Season 22
CSL 2026 AUTUMN (S22)
Acropolis #5
Acropolis #5 - GSA
Calamity Invitational
Logitech G Play Connect 2026
SL StarSeries Fall 2026
FISSURE Playground #3
BLAST Open Fall 2026
Esports World Cup 2026
BLAST Bounty Summer 2026
BLAST Bounty Summer Qual
Stake Ranked Episode 3
XSE Pro League 2026

Upcoming

Acropolis #5 - GSB
Acropolis #5 - GSC
BSL Season 23
SC4ALL II: Brood War
BSL 23: Non-Korean Championship
HSC XXX
Stellar Fest 2: Lunar Cup
SC4ALL II: StarCraft II
Kung Fu Cup 2026 Grand Finals
RSL Offline Finals
Copium Cup
PGL Major Singapore 2026
Stake Ranked Episode 6
BLAST Rivals Fall 2026
IEM Beijing 2026
Stake Ranked Episode 5
PGL Masters Bucharest 2026
1win Private Club #2
Thunderpick World Champ. '26
ESL Pro League Season 24
Stake Ranked Episode 4
1win Private Club #1
TLPD

1. ByuN
2. TY
3. Dark
4. Solar
5. Stats
6. Nerchio
7. sOs
8. soO
9. INnoVation
10. Elazer
1. Rain
2. Flash
3. EffOrt
4. Last
5. Bisu
6. Soulkey
7. Mini
8. Sharp
Sidebar Settings...

Advertising | Privacy Policy | Terms Of Use | Contact Us

Original banner artwork: Jim Warren
The contents of this webpage are copyright © 2026 TLnet. All Rights Reserved.