• Log InLog In
  • Register
Liquid`
Team Liquid Liquipedia
EST 07:47
CET 13:47
KST 21:47
  • Home
  • Forum
  • Calendar
  • Streams
  • Liquipedia
  • Features
  • Store
  • EPT
  • TL+
  • StarCraft 2
  • Brood War
  • Smash
  • Heroes
  • Counter-Strike
  • Overwatch
  • Liquibet
  • Fantasy StarCraft
  • TLPD
  • StarCraft 2
  • Brood War
  • Blogs
Forum Sidebar
Events/Features
News
Featured News
[ASL22] Finals Preview: Sweet Victory!12[ASL22] Ro4 Preview: Mirror Mirror6[ASL22] Ro8 Preview: Within Reach5[ASL22] Ro8 Preview: In A Tizzy11[ASL22] Ro16 Preview: Holy Diver5
Community News
[BSL23] RO16 Group Stage14Weekly Cups (Nov 2-8): herO back on top?2Weekly Cups (Oct 26 - Nov 1): MaxPax, herO, Solar win0Weekly Cups (October 19-25): Clem triples first in 5.0.175Evil Geniuses - shutting down23
StarCraft 2
General
Serral's getting trashed by New Catsle's Mind Weekly Cups (Nov 2-8): herO back on top? Liquibets sc2 season 30 No more SC2 streamers on team liquid? StarCraft open world shooter announced at BlizzCon
Tourneys
soO & FanTaSy return! SC2 Kevin Scrim 4v4 (Nov 16) RSL goes to London! 2026 Offline Finals Nov 21-22 Tasteless Time Warp: SC Evo Showmatch (May 25) Sparkling Tuna Cup - Weekly Open Tournament iNu's Battles #22
Strategy
[H] ZvP Mid-Late Game: Stalkers Collossi HT
Custom Maps
Starcraft 2 Advance [G] How to playtest arcade maps [D] the control group Simple Questions/Answers
External Content
The PondCast: SC2 News & Results Mutation # 551 Robotic Revival Mutation # 550 Graveyard Shift Mutation # 549 Endless Sparkles
Brood War
General
List of top players active on ShieldBattery BW General Discussion [BSL23] RO16 Group Stage screpdb: new Starcraft reporting tool [BW] Looking for Clan Thread!
Tourneys
KCM Race Survival 2026 Season 4 BWCL Season 65 Announcement [Megathread] Daily Proleagues [BSL23] Ro16 Group C - Sunday 21:00 CET
Strategy
Infested Terran strategies in 2026 Nuke strategy worked in K-League 2026-11-09 50,000-Word Terran Builds Memo 2026-10-22 Cliff Jump Revisited (1 in a 1000 strategy)
Other Games
General Games
List of Game Threads The PlayStation 5 Stormgate/Frost Giant Megathread Nintendo Switch Thread Path of Exile
Dota 2
Can Game Data Analytics Help Players Improvements
League of Legends
[TL LoL EUW IHs] Teemo shall perish
Heroes of the Storm
Heroes of the Storm 2.0
Hearthstone
Deck construction bug
TL Mafia
TL Mafia Community Thread
Community
General
Trading/Investing Thread European Politico-economics QA Mega-thread Russo-Ukrainian War Thread Dating: How's your luck? US Politics Mega-thread
Fan Clubs
Fan Club Resource Thread Reynor Fan Club The Flash Fan Club
Media & Entertainment
Movie Discussion! Anime Discussion Thread [Manga] One Piece
Sports
Football (Soccer) Thread TeamLiquid Health and Fitness Initiative For 2023 MLB/Baseball 2023
World Cup 2022
Tech Support
Computer Build, Upgrade & Buying Resource Thread
TL Community
The Automated Ban List Recent Gifted Posts
Blogs
The time I organised my…
AssyrianKing
Why I built Repalyzer (1.1.…
BlueStar
Innovate or Game Over?
TrAiDoS
ShieldBattery on Mac
Kraekkling
[ASL22] Ro4 Day1 Ticket Giv…
bITt.mAN
Can Bots Beat Pros?? Starcr…
namkraft
Customize Sidebar...

Website Feedback

Closed Threads


Active: 14798 users

My Car Loan

Blogs > micronesia
Post a Reply
1 2 Next All
micronesia
Profile Blog Joined July 2006
United States24813 Posts
Last Edited: 2011-04-21 22:52:12
April 21 2011 22:49 GMT
#1
[image loading]


+ Show Spoiler [Data] +

Here is the code for the "New Balance" cells: =D2*(1+$H$1/12)

As I dragged the code down to each additional cell the D2 stepped to D3, D4, etc. H1 is the cell which has the interest rate of 0.0499.

[image loading]


*****
ModeratorThere are animal crackers for people and there are people crackers for animals.
Cauld
Profile Joined February 2010
United States350 Posts
Last Edited: 2011-04-21 23:01:33
April 21 2011 23:00 GMT
#2
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.
micronesia
Profile Blog Joined July 2006
United States24813 Posts
Last Edited: 2011-04-21 23:03:36
April 21 2011 23:02 GMT
#3
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.
ModeratorThere are animal crackers for people and there are people crackers for animals.
eNtitY~
Profile Joined January 2007
United States1293 Posts
April 21 2011 23:05 GMT
#4
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/
http://www.starcraftdream.com
micronesia
Profile Blog Joined July 2006
United States24813 Posts
April 21 2011 23:08 GMT
#5
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).
ModeratorThere are animal crackers for people and there are people crackers for animals.
Cauld
Profile Joined February 2010
United States350 Posts
Last Edited: 2011-04-21 23:15:12
April 21 2011 23:11 GMT
#6
On April 22 2011 08:02 micronesia wrote:
Show nested quote +
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.
eNtitY~
Profile Joined January 2007
United States1293 Posts
Last Edited: 2011-04-21 23:15:30
April 21 2011 23:14 GMT
#7
On April 22 2011 08:08 micronesia wrote:
Show nested quote +
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).


Yeah just checked, it's 9.4 and I've already paid $4000 in interest .

I'll end up paying ~$10k in interest before it's done. I also co-signed with my dad (Very high 700s CS) but didn't do automatic payments and also had a 72 month contract.
http://www.starcraftdream.com
Ryps
Profile Blog Joined May 2010
Romania2740 Posts
Last Edited: 2011-04-21 23:16:47
April 21 2011 23:14 GMT
#8
So... what car did you get ? and whos pic is at the bottom
Looks like its a mazda hatchback ?
Myles
Profile Blog Joined March 2010
United States5162 Posts
April 21 2011 23:18 GMT
#9
On April 22 2011 08:08 micronesia wrote:
Show nested quote +
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).


Yea, you got 3.3% lower rate than I did when I co-signed with my dad for a 17k loan in '07. Of course, now that I'm older/wiser I feel I could have got a better deal, but that's life.
Moderator
eNtitY~
Profile Joined January 2007
United States1293 Posts
April 21 2011 23:23 GMT
#10
Fuck you both.
http://www.starcraftdream.com
tofucake
Profile Blog Joined October 2009
Hyrule19269 Posts
April 21 2011 23:24 GMT
#11
Your last payment is off because that's how it works out. Your last payment due will only be for the remaining principal, as you'll have paid off the interest on the 59th payment.

As for the payment, you're close. It's actually
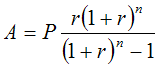
[image loading]
Where r is the periodic interest rate. For calculating payments, it'll be daily. The reason your interest decreases over time is because at the start of the loan, you have a higher principal balance (P above).

The actual payment (assuming Simple Interest here) is:
Fees = Total amount paid minus any fee balance (late fees, typically)
Interest = Current principal balance times the periodic interest rate (APR / 365) times the number of days since last payment plus any outstanding interest due
Principal is the rest

On an Actuarial loan, that 365 could be 360, 363, or 365.
On a Rule of 78s loan you're getting totally shafted in every way possible (Ro78s is illegal in 17 states because of it's terribadness)

What this means is that, as long as you don't have a Rule of 78s loan, paying early and overpaying will reduce overall how much you pay. This may seem counter intuitive (wtf pay more = pay less?) but the financing company (or bank) gets all of its profit off of the interest. By overpaying you prematurely reduce the principal balance, so if you paid $400 every month instead of $377.56 you'd end up paying off the loan a couple months early, which reduces the number of days calculated for how much interest is due (so you don't pay that interest at all).

By paying early, you're cutting short the number of days interest is calculated on as well. For example, if you payed May 1st, you'd put $40.84, but if you pay a day earlier $39.48. So that's another $1.36 that goes directly to principal, which will reduce how much you pay next month.
Liquipediaasante sana squash banana
tofucake
Profile Blog Joined October 2009
Hyrule19269 Posts
April 21 2011 23:25 GMT
#12
On April 22 2011 08:11 Cauld wrote:
Show nested quote +
On April 22 2011 08:02 micronesia wrote:
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.
Principal never ever ever increases by anything other than a bounced check. EVER
Liquipediaasante sana squash banana
Michaelj
Profile Joined February 2008
United States186 Posts
April 21 2011 23:26 GMT
#13
They're not "front-loading" the interest. They do calculate your payments such that you can 60 equal payments. But if your loan agreement allows you to prepay your loan, you would find that you could just pay for the remaining principal, and not pay any of the extra interest.

Example:

$20,000 loan
1% interest
$300 monthly payment

Period 1: $20,000 remaining principal, $200 interest payment, $100 principal payment
Period 2: $19,900 remaining principal, $199 interest payment, $101 principal payment
Period 3: $19,799 remaining principal, $198 interest payment, $102 principal payment

So you see it's pretty clear that you are just paying the interest on the principal that you currently have outstanding. The car companies have just adjusted your monthly payment amount such that you pay an even amount every month, and everything takes care of itself neatly by the time you 5 years are up.

TLDR: The suggested payment amount presumes you take the full 5 years to pay. If you have $15k in principal left, and want to pay if off in full today, you can and not pay a dime of extra interest
---
Michaelj
Profile Joined February 2008
United States186 Posts
April 21 2011 23:28 GMT
#14
On April 22 2011 08:25 tofucake wrote:
Show nested quote +
On April 22 2011 08:11 Cauld wrote:
On April 22 2011 08:02 micronesia wrote:
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.
Principal never ever ever increases by anything other than a bounced check. EVER


You'd be surprised... in the housing boom people would get negative amortization loans that meant they would pay LESS than interest. They'd try to flip the house as soon as they could.

http://en.wikipedia.org/wiki/Negative_amortization
---
micronesia
Profile Blog Joined July 2006
United States24813 Posts
April 21 2011 23:30 GMT
#15
On April 22 2011 08:11 Cauld wrote:
Show nested quote +
On April 22 2011 08:02 micronesia wrote:
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.

If you are right (and what you said makes sense) then my payoff amount at the end of the first month would have just been the 20,083 dollars... I might be remembering incorrectly but I am pretty sure that's not what it was. If it WAS then it works exactly how my 'high school math class' explained and is consistent with your explanation.

Do you know why they inform me in my loan information how much of my payment went to interest and how much went to principal? Was it just to show how much interest I accrued that prior month? And I guess also to show how much I knocked down the principal that month?
ModeratorThere are animal crackers for people and there are people crackers for animals.
micronesia
Profile Blog Joined July 2006
United States24813 Posts
Last Edited: 2011-04-21 23:35:29
April 21 2011 23:34 GMT
#16
On April 22 2011 08:24 tofucake wrote:
Your last payment is off because that's how it works out. Your last payment due will only be for the remaining principal, as you'll have paid off the interest on the 59th payment.

As for the payment, you're close. It's actually
[image loading]
Where r is the periodic interest rate. For calculating payments, it'll be daily. The reason your interest decreases over time is because at the start of the loan, you have a higher principal balance (P above).

The actual payment (assuming Simple Interest here) is:
Fees = Total amount paid minus any fee balance (late fees, typically)
Interest = Current principal balance times the periodic interest rate (APR / 365) times the number of days since last payment plus any outstanding interest due
Principal is the rest

On an Actuarial loan, that 365 could be 360, 363, or 365.
On a Rule of 78s loan you're getting totally shafted in every way possible (Ro78s is illegal in 17 states because of it's terribadness)

What this means is that, as long as you don't have a Rule of 78s loan, paying early and overpaying will reduce overall how much you pay. This may seem counter intuitive (wtf pay more = pay less?) but the financing company (or bank) gets all of its profit off of the interest. By overpaying you prematurely reduce the principal balance, so if you paid $400 every month instead of $377.56 you'd end up paying off the loan a couple months early, which reduces the number of days calculated for how much interest is due (so you don't pay that interest at all).

By paying early, you're cutting short the number of days interest is calculated on as well. For example, if you payed May 1st, you'd put $40.84, but if you pay a day earlier $39.48. So that's another $1.36 that goes directly to principal, which will reduce how much you pay next month.

Oh okay I should have realized that it compounds daily instead of monthly... well I guess that information wasn't given to me directly so I can't blame myself for not knowing :p

And I guess from what I'm reading the type of 'front loading' I am thinking of would only happen with special conditions in the agreement.

On April 22 2011 08:26 Michaelj wrote:
They're not "front-loading" the interest. They do calculate your payments such that you can 60 equal payments. But if your loan agreement allows you to prepay your loan, you would find that you could just pay for the remaining principal, and not pay any of the extra interest.

Example:

$20,000 loan
1% interest
$300 monthly payment

Period 1: $20,000 remaining principal, $200 interest payment, $100 principal payment
Period 2: $19,900 remaining principal, $199 interest payment, $101 principal payment
Period 3: $19,799 remaining principal, $198 interest payment, $102 principal payment

So you see it's pretty clear that you are just paying the interest on the principal that you currently have outstanding. The car companies have just adjusted your monthly payment amount such that you pay an even amount every month, and everything takes care of itself neatly by the time you 5 years are up.

TLDR: The suggested payment amount presumes you take the full 5 years to pay. If you have $15k in principal left, and want to pay if off in full today, you can and not pay a dime of extra interest

I hope you are right and that's how my loan is working because that's better for us!
ModeratorThere are animal crackers for people and there are people crackers for animals.
tofucake
Profile Blog Joined October 2009
Hyrule19269 Posts
April 21 2011 23:40 GMT
#17
On April 22 2011 08:28 Michaelj wrote:
Show nested quote +
On April 22 2011 08:25 tofucake wrote:
On April 22 2011 08:11 Cauld wrote:
On April 22 2011 08:02 micronesia wrote:
On April 22 2011 08:00 Cauld wrote:
I don't think interest is calculated in any crazy way. Take the principle and multiply by 1 + the percentage rate divided by the number of payments/year. That's your new principle.

So for your first payment:
0.0499/12 ~ 0.00416 + 1 = 1.00416
1.00416*20,000 = 20083.17

So your interest is compounded monthly and your payment is setup to pay off the loan in the desired time frame. There's no front loading the interest, the interest is based on the principle which naturally decreases over time.

I believe when my loan started my payoff amount was significantly higher than my 20k balance plus my first payment, thus, front loaded interest.

edit: can't you also see it clearly in the first graph? That information was given to me directly.


No. The interest is based on the principle. So as you make payments and the principle decreases, so does the interest amount. Since your payment is staying the same and is greater than the monthly interest the additional payment is applied to the principle. The next month the principle is smaller, so the interest amount also smaller, etc.

Your payment amount is setup so that the remaining principle after the desired number of payments is 0. But, its possible to have a loan where you only pay interest, and principle increases each month (your payment would have to be less than the monthly interest). After a given amount of time your payment increases and then you begin to pay down the principle.

Just do a couple of the monthly calculations and you'll see how it goes.

They can tell you that over the course of the loan how much you will end up paying. But there's nothing stopping you from paying off the balance at any point and not paying any remaining interest (except for a clause in your contract that may forbid, or have a penalty, for early repayment).

What you're looking at is even more pronounced in the case of a 30-year mortgage. That's just how paying off a loan works.

I guess if you wanted to call it front loaded interest you could, but I don't think that's an accurate description of the situation. In my mind front loaded interest would be something where your rate is %10 for the first 2 years and then drops to 2%.
Principal never ever ever increases by anything other than a bounced check. EVER


You'd be surprised... in the housing boom people would get negative amortization loans that meant they would pay LESS than interest. They'd try to flip the house as soon as they could.

http://en.wikipedia.org/wiki/Negative_amortization

Yes but those were sub-prime house loans, not car loans. Please trust me. This is literally what I do for a living.
Liquipediaasante sana squash banana
Cauld
Profile Joined February 2010
United States350 Posts
April 21 2011 23:53 GMT
#18
I was speaking in the general sense about loans, I wouldn't ever expect a car loan to allow a payment less than the interest amount, since the underlying asset is generally decreasing in value over time.
a176
Profile Blog Joined August 2009
Canada6688 Posts
April 22 2011 00:01 GMT
#19
On April 22 2011 08:14 eNtitY~ wrote:
Show nested quote +
On April 22 2011 08:08 micronesia wrote:
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).


Yeah just checked, it's 9.4 and I've already paid $4000 in interest .

I'll end up paying ~$10k in interest before it's done. I also co-signed with my dad (Very high 700s CS) but didn't do automatic payments and also had a 72 month contract.


why in the world would you agree to an-almost 10% interest rate, completely ridiculous
starleague forever
eNtitY~
Profile Joined January 2007
United States1293 Posts
Last Edited: 2011-04-22 00:12:11
April 22 2011 00:10 GMT
#20
On April 22 2011 09:01 a176 wrote:
Show nested quote +
On April 22 2011 08:14 eNtitY~ wrote:
On April 22 2011 08:08 micronesia wrote:
On April 22 2011 08:05 eNtitY~ wrote:
Weird, I also got a $20,000 Car loan in 2008. I think I'm paying much more than $2653 in interest though :/

Do you know your interest rate? I cosigned with my dad and agreed for automatic payments from my checking account so I got a pretty good rate for the time (summer 2k8).


Yeah just checked, it's 9.4 and I've already paid $4000 in interest .

I'll end up paying ~$10k in interest before it's done. I also co-signed with my dad (Very high 700s CS) but didn't do automatic payments and also had a 72 month contract.


why in the world would you agree to an-almost 10% interest rate, completely ridiculous


Well....

[image loading]

And being 20.


Man that was retarded. Can you refinance auto loans if your car is worth more than the balance?
http://www.starcraftdream.com
1 2 Next All
Please log in or register to reply.
Live Events Refresh
WardiTV Invitational
21:00
WardiTV Not-Summer Championshi
Lambo vs Shameless
Rogue vs uThermal
Percival vs YoungYakov
TBD vs GgMaChine
WardiTV433
ComeBackTV 364
Rex90
LiquipediaDiscussion
[ Submit Event ]
Live Streams
Refresh
StarCraft 2
mouzHeroMarine 257
ProTech141
Rex 90
Classic 14
StarCraft: Brood War
Britney 32355
Rain 1894
Jaedong 694
Mini 375
EffOrt 369
Light 289
Shuttle 251
Larva 250
firebathero 170
Snow 165
[ Show more ]
Killer 162
Rush 159
Last 150
Stork 144
Hyun 113
Pusan 104
Aegong 75
Movie 62
Sea.KH 58
hero 48
Shinee 44
ToSsGirL 31
soO 24
Hm[arnc] 23
Noble 22
sorry 19
Barracks 18
Free 12
Sacsri 10
Terrorterran 8
Icarus 4
yabsab 4
Dota 2
Dendi1506
monkeys_forever347
XcaliburYe184
Gorgc31
Counter-Strike
fl0m3370
olofmeister839
allub173
kRYSTAL_26
Other Games
singsing1539
B2W.Neo784
Lowko300
XaKoH 224
syndereN182
crisheroes167
Mew2King92
ArmadaUGS47
Organizations
StarCraft 2
angryscii 19
StarCraft: Brood War
lovetv 7
[ Show 12 non-featured ]
StarCraft 2
• AfreecaTV YouTube
• intothetv
• Kozan
• IndyKCrew
• Migwel
StarCraft: Brood War
• ChaeLyn 6
• BSLYoutube
• STPLYoutube
• ZZZeroYoutube
Dota 2
• WagamamaTV567
League of Legends
• Jankos2341
• Stunt518
Upcoming Events
OSC
3h 14m
OSC
10h 14m
ArT vs MindelVK
MiniZergUA vs TBD
Shameless vs TBD
Ultimate Battle
23h 14m
OSC
1d 1h
OSC
1d 10h
ByuN vs MaxPax
herO vs Krystianer
Percival vs Shameless
LetaleX vs YoungYakov
Nicoract vs Gerald
GgMaChine vs ArT
CranKy Ducklings
1d 21h
WardiTV Invitational
1d 23h
IPSL
2 days
TerrOr vs IJ_Terran
rasowy vs Hazorath
BSL
2 days
TerrOr vs OyAji
UltrA vs Gosudark
Sparkling Tuna Cup
2 days
[ Show More ]
WardiTV Invitational
2 days
IPSL
3 days
Art_Of_Turtle vs KameZerg
Radley vs George
BSL
3 days
Artosis vs Dewalt
Ret vs Tech
WardiTV Weekly
3 days
PiGosaur Cup
5 days
The PondCast
5 days
GSL
6 days
Liquipedia Results

Completed

Proleague 2026-11-11
Blizzard Classic Cup 2026
HCC Season 3

Ongoing

Acropolis #5
KCM Race Survival 2026 Season 4
International ShieldBattery League
Individual League
BSL Season 23
IPSL Winter 2026-27
Calamity Cup Div. A Season 8
BLAST Rivals Fall 2026
IEM Beijing 2026
PGL Masters Bucharest 2026
Stake Ranked Episode 5
1win Private Club #2
Thunderpick World Champ. '26
ESL Pro League Season 24
Stake Ranked Episode 4
1win Private Club #1
Logitech G Play Connect 2026
SL StarSeries Fall 2026
FISSURE Playground #3
BLAST Open Fall 2026

Upcoming

YSL S4
Sector 591
SC4ALL II: Brood War
BSL 23: Non-Korean Championship
HSC XXX
Stellar Fest 2: Lunar Cup
StarCraft2 Weekly Open Tournament 2026 Grand Finals
SC4ALL II: StarCraft II
Kung Fu Cup 2026 Grand Finals
RSL Offline Finals
Underdog Cup 2026 Div 2-3
PGL Bucharest 2027
BLAST Bounty Winter 2027
PGL Major Singapore 2026
Stake Ranked Episode 6
TLPD

1. ByuN
2. TY
3. Dark
4. Solar
5. Stats
6. Nerchio
7. sOs
8. soO
9. INnoVation
10. Elazer
1. Rain
2. Flash
3. EffOrt
4. Last
5. Bisu
6. Soulkey
7. Mini
8. Sharp
Sidebar Settings...

Advertising | Privacy Policy | Terms Of Use | Contact Us

Original banner artwork: Jim Warren
The contents of this webpage are copyright © 2026 TLnet. All Rights Reserved.